




Menu


This page may contain paid affiliate links. If you buy or register through them, MyFxBots may earn a commission or referral fee. See our disclaimer for details.

DowX is an MT5 Expert Advisor confined to one instrument, the Dow30 index, and to one scalping window: a buy stop and a sell stop go in two minutes after the US cash open; unfilled orders are cancelled, and any position is closed before the session ends. The published stop is 90 index points, and the inputs carry a recovery multiplier worth checking before purchase.
Trading Idea
The vendor's premise for DowX is that the Dow30's opening minutes produce enough displacement for a two-sided stop entry to catch a direction, and that a 90-point stop with a trailing exit takes most of the move before it fades. Nothing in the system forecasts direction; it is built to be present when the open resolves and to leave early when it does not.
Specifications
Recommended broker and VPS
A system that enters twice within two minutes of the cash open needs the fill it asked for, and index spreads at the open are where that is decided. Tickmill, and IC Markets is a sensible place to start the account, and TradingFX VPS VPS removes the home connection from the equation. Neither is a condition of the licence.
MT5 version availability
MT5 is the only build: the product page lists MT5 as the platform, and no MT4 edition is sold. A trader still on MT4 would have to change terminals before this system can run, and the published reports are MT5 strategy-tester output from the same version line.
User guide inclusion
A purchase delivers a download link for the executable, together with a guide, and a client area where account numbers are held. Installation help is therefore documented rather than assumed, and the published inputs are the practical reference for the settings that matter.
Customer support
Email at [email protected] and Telegram at t.me/quotraderfx are the two published routes to support, and licence work is handled through the client area rather than by a person. The only stated support window on the site sits in the MBT product block, not here, which makes response time for this system a question to put to the vendor.
Recommended trading account criteria
The system is published for private and prop-firm accounts alike, and separate tests are supplied for each: one run in a private-account configuration and one in the prop configuration, both on US dollar accounts. Whether a given firm permits a market-open index strategy has to be checked against its rules rather than against this page.
Installer
Delivery is a download link plus a user guide, with no installer wizard described. In practice, the buyer receives a compiled MT5 file and attaches it to a Dow30 chart, which is what the guide is there to walk through.
Refund Policy
The guarantee is 14 days across the vendor's products, described as no-fuss. A separate note in the MBT licence block says that a refunded EA stops working, so the window and the consequence of using it should be read together.
Supported Currency Pairs
US30 (Dow30 USA Index)
MetaTrader Chart Timeframe
H1
3rd Party-Verified DowX's Live Trading Result Statements
The product page for DowX links four Myfxbook records instead of screenshots: account #1 at EqualMarkets, #2 at MarketMates, #3 at ICMarkets, and #4 at ThinkMarkets labelled PROP SETTING, all retrieved on 4 November 2026. Hosting them on an independent tracker is the right instinct, because a trade list and a drawdown curve held outside the vendor's control can be opened and inspected by anyone prepared to register.
Their contents could not be read for this review. The pages served to the desk arrived with their navigation and no figures, and opening accounts on tracking services to read a vendor's records is not something the desk does. The vendor states that the records update in real time and that each shows deposit, leverage, currency, account type, and the start of history.
Two limits frame the evidence, whatever those pages turn out to show. The fourth record's label names a configuration, PROP SETTING, rather than a funded prop account. And whatever any one of those accounts shows, past performance does not predict future results.
Real Money Account

Started On
May 26, 2026
Leverage
1:100
Broker
Equal Markets
Starting Balance
$6000
Total Gain
+181.35%
Live Test Summary
Started On
May 26, 2026
Account Leverage
1:100
Profit Factor
2.45
Total Gain
+181.35%
Absolute Gain
+37.58%
Monthly Gain
24.88%
Daily Gain
0.75%
Total Pips
1,163.5
Total Trades
47
Profit Amount
$2,255.09
(%) Won Trades
1,163.5
Drawdown
9.39%

Started On
May 26, 2026
Leverage
1:1000
Broker
MarketMates
Starting Balance
$1000
Total Gain
+200.46%
Live Test Summary
Started On
May 26, 2026
Account Leverage
1:1000
Profit Factor
2.64
Total Gain
+200.46%
Absolute Gain
+200.47%
Monthly Gain
27.54%
Daily Gain
0.79%
Total Pips
1,150.7
Total Trades
45
Profit Amount
$2,004.65
(%) Won Trades
1,150.7
Drawdown
10.01%
Real Money Account

Live Test Summary
Started On
Aug 17, 2026
Account Leverage
1:500
Profit Factor
3.12
Total Gain
+43.18%
Absolute Gain
+27.69%
Monthly Gain
22.68%
Daily Gain
0.64%
Total Pips
331.7
Total Trades
16
Profit Amount
(%) Won Trades
331.7
Drawdown
10.04%

Started On
Aug 24, 2026
Leverage
1:500
Broker
ThinkMarkets
Starting Balance
$100000
Total Gain
+5.07%
Live Test Summary
Started On
Aug 24, 2026
Account Leverage
1:500
Profit Factor
2.15
Total Gain
+5.07%
Absolute Gain
+5.07%
Monthly Gain
3.03%
Daily Gain
0.10%
Total Pips
160.5
Total Trades
15
Profit Amount
$5,069.79
(%) Won Trades
160.5
Drawdown
2.25%
What the four links establish is that the vendor submits to outside tracking; what they do not establish is anything about the trading, because the figures sit behind a sign-in. A reader prepared to register on Myfxbook can settle the question in an afternoon, and it is the first step worth taking before a licence is paid for.
DowX's Backtests by MetaTrader Strategy Tester using High-Quality Historical Tick Data
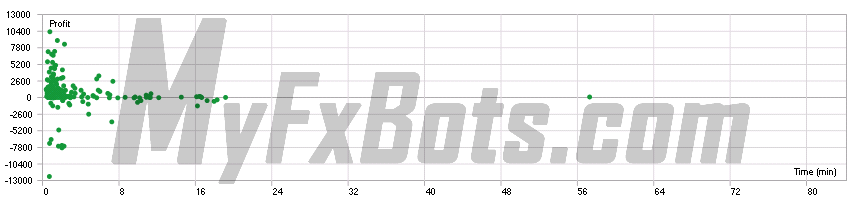
The product page for DowX publishes a ZIP archive of MT5 strategy-tester output rather than a single equity curve, and the desk downloaded and opened it on 4 November 2026. Two reports sit inside: one run on a standard retail account, one on the prop configuration, both on the Dow30 index, both tested over the same window and both replayed from one broker's tick data at full history quality.
What they show, in outline, is profit on both configurations, the same trade sequence behind each, and the difference between them confined to position size — the prop run reaches its result on a far larger deposit at a small fraction of the risk. The profit rests on a high proportion of winners whose average is smaller than the average loser, and in each report the deepest balance drawdown coincides exactly with the longest losing run. That coincidence, not the headline return, is what decides how large an account has to be.
Because the two runs differ only in sizing inputs, every difference in outcome traces to the risk percentage and the deposit rather than to different logic. The headline on the page belongs to the prop run's scale of risk, not to the standard one.
This is modelling, not live trading. The tester replays ticks from one broker's feed; no spread, commission, or swap setting is printed anywhere in either document, and Dow30 spreads widen at the cash open — the minute this system trades. Past performance does not predict future results, and the sample window is short enough that a favourable run of this length cannot settle the question either way.
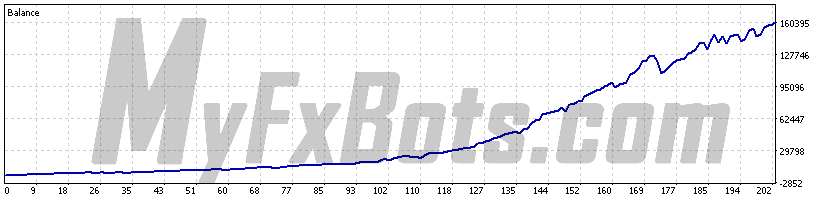
Statement 1 is the standard-configuration report for DowX described in the MT backtesting results section, taken from the vendor's archive on 4 November 2026. It runs the Dow30 index on an hourly chart over the same window as its sibling, on a retail account, and its log is detailed enough to read trade by trade: long and short entries in a similar split, a high proportion of winners on both sides, and average winners consistently smaller than average losers.
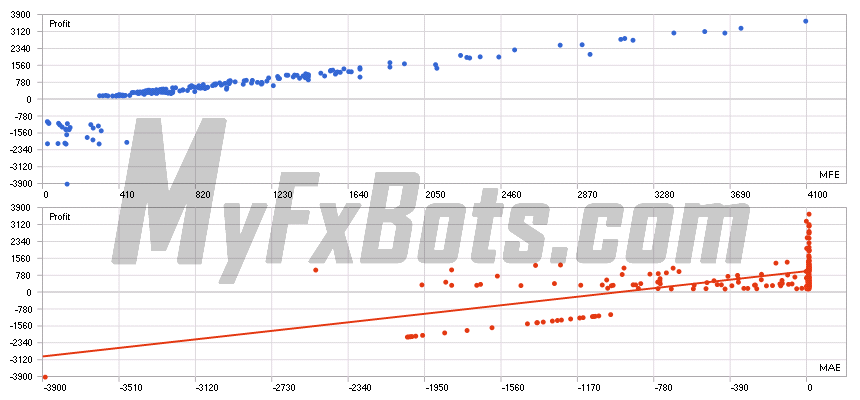
Two features of the log matter more than the totals. The deepest balance drawdown coincides exactly with the longest losing run in the log, so the tested risk was one short burst of losses rather than a slow accumulation — a slightly longer run would have gone past it. And the largest single loss stands far above the average loss, which is what position size rising inside a losing run looks like; the report does not label the trades, so the cause cannot be confirmed.
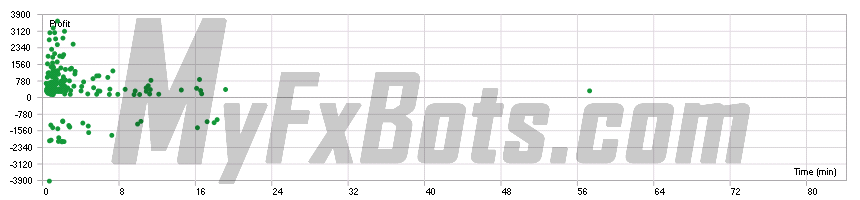
One session departs from the routine. A pending pair placed at the open was still live the following morning, hours outside the two-minute design, when one side filled and closed on its stop shortly after. It is a single departure across the whole log, and neither the report nor the site explains it.
The statement is modelling. It replays ticks from one broker's feed, the spread, commission and swap inputs behind its fills are never disclosed, and a live account on different conditions will diverge. Past performance does not predict future results.
Backtests Settings
Symbol
US30
Period
H1 (2025.01.01 - 2026.08.27)
Broker
Currency
USD
Leverage
1:500
Symbols
1
Bars in test
9741
Ticks modelled
65228575
Modelling quality
100%
Initial Deposit
$5000.00
Backtests Results
Total net profit
157036.32
Gross profit
235280.20
Gross loss
-78243.88
Profit factor
3.01
Expected payoff
777.41
Margin level
325.85%
Absolute Bal DD
0.00
Maximal Bal DD
18 747.18 (14.68%)
Relative Bal DD
14.68% (18 747.18)
Absolute EQ DD
37.66
Maximal EQ DD
27 447.61 (21.25%)
Relative EQ DD
21.25% (27 447.61)
Recovery Factor
5.72
Sharp Ratio
39.73
Z-Score
1.53 (87.40%)
AHPR
1.0179 (1.79%)
LR Correlation
0.90
OnTester result
-
GHPR
1.0174 (1.74%)
LR Standard Error
21230.10
Total Trades
202
Short positions
85 (88.24%)
Long positions
117 (87.18%)
Profit trades
177 (87.62%)
Loss trades
25 (12.38%)
Largest Profit trade
10404.73
Largest Loss trade
-12271.17
Average Profit trade
1329.27
Average Loss trade
-3129.76
Maximum consecutive wins (profit in money)
21 (22 817.97)
Maximum consecutive losses (loss in money)
2 (-18 747.18)
Maximal consecutive profit (count of wins)
33 412.83 (10)
Maximal consecutive loss (count of losses)
-18 747.18 (2)
Avarage consecutive wins
7
Avarage consecutive losses
1
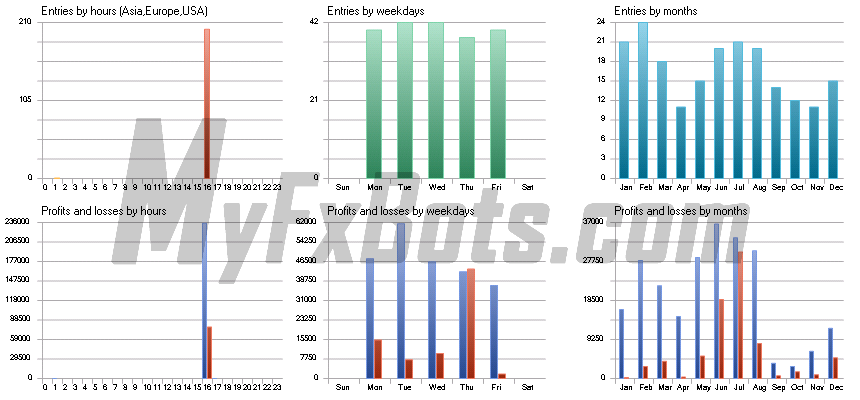
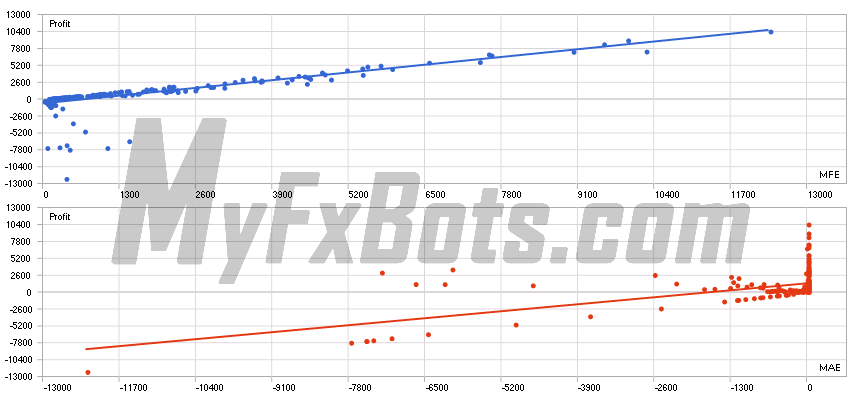
The run is internally consistent and detailed enough to check, and everything above is read from it rather than estimated. What it cannot show is whether a drawdown produced by one short burst of losses stays that contained when a real index feed slips on the entry.
Statement 2 carries the prop configuration: the same index, chart, and window, a much larger deposit, a starting risk set at a fraction of the standard run's, and a correspondingly lower ceiling on it. Its trade sequence is the same one — the same entries, the same win rate, the same longest losing run — because only the sizing inputs differ.
That deserves stating plainly, because it means the prop report's calmer drawdown is arithmetic rather than evidence of a better system: the same trades, taken smaller, on a bigger account. The largest win and the largest loss shrink in proportion, and the equity drawdown stays inside a band a firm's rules could plausibly tolerate over a period — which is not the same as tolerating any single day.
The limitation is the same one: a model, run on one feed, under assumptions the report does not print, with past performance no guide to what comes next.
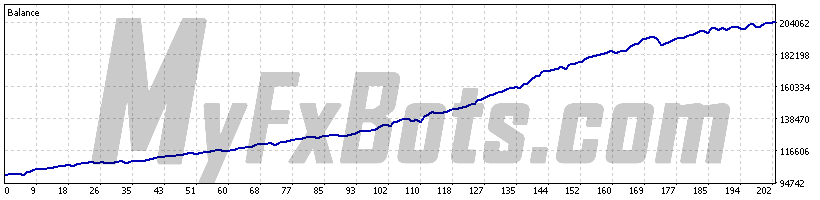
Backtests Settings
Symbol
US30
Period
H1 (2025.01.01 - 2026.08.27)
Broker
Currency
USD
Leverage
1:500
Symbols
1
Bars in test
9741
Ticks modelled
65228575
Modelling quality
100%
Initial Deposit
$100000.00
Backtests Results
Total net profit
105161.19
Gross profit
144776.45
Gross loss
-39615.26
Profit factor
3.65
Expected payoff
520.60
Margin level
1669.55%
Absolute Bal DD
0.00
Maximal Bal DD
5 872.02 (3.01%)
Relative Bal DD
3.01% (5 872.02)
Absolute EQ DD
149.30
Maximal EQ DD
8 828.82 (4.52%)
Relative EQ DD
4.52% (8 828.82)
Recovery Factor
11.91
Sharp Ratio
40.79
Z-Score
1.53 (87.40%)
AHPR
1.0036 (0.36%)
LR Correlation
0.98
OnTester result
-
GHPR
1.0036 (0.36%)
LR Standard Error
7162.48
Total Trades
202
Short positions
85 (88.24%)
Long positions
117 (87.18%)
Profit trades
177 (87.62%)
Loss trades
25 (12.38%)
Largest Profit trade
3622.97
Largest Loss trade
-3899.08
Average Profit trade
817.95
Average Loss trade
-1584.61
Maximum consecutive wins (profit in money)
21 (18 687.34)
Maximum consecutive losses (loss in money)
2 (-5 872.02)
Maximal consecutive profit (count of wins)
18 687.34 (21)
Maximal consecutive loss (count of losses)
-5 872.02 (2)
Avarage consecutive wins
7
Avarage consecutive losses
1
What this statement does not answer is the question a prop trader actually has. Firms write their limits around a daily loss and an intraday or trailing floor, while a period maximum is a different measurement, and the report does not break its drawdown down by day. That gap is closed with the firm's rulebook and a demo run, not with this report.
The archive establishes that the logic was run on two deposits at two risk settings and produced a coherent trade sequence in each, which is more than a teaser. It does not establish execution at a live index spread, and it says nothing about a broker whose US30 quote is wider than the one modelled here.
DowX's Trading Strategy
What is submitted, and when
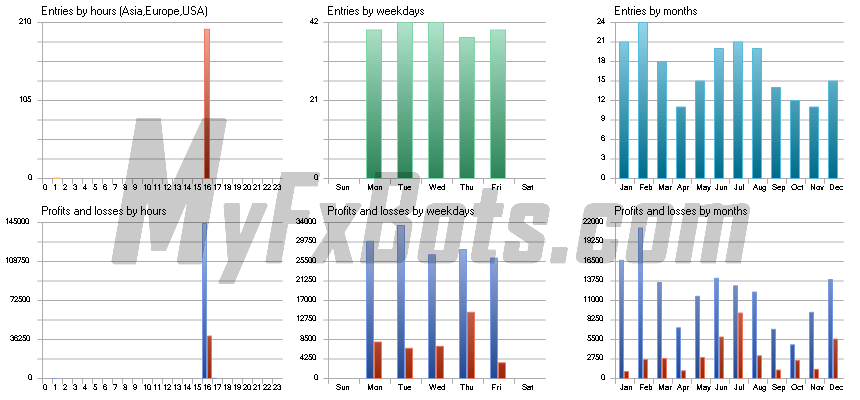
This is breakout trading on a clock rather than on a chart pattern. The published order log repeats the same routine every session: at 16:30:02 server time, a buy stop is placed above the market and a sell stop below it, each carrying a stop and a target 9,000 points away — 90.00 index points in the report's own price cells. If neither triggers, both are cancelled at 16:32:00, which turns the vendor's "first few minutes" into a two-minute parameter. The product page mentions two sets of straddle orders; the log shows one buy stop and one sell stop per session.
Managing the filled position
When one side fills, the other is cancelled in the same second, and the position is handed to the trailing stop. Trailing begins at 2,500 points of open profit, keeps 1,000 points behind price and steps in 1,000-point increments; break-even is switched off in both reports. A position still open at 22:00 server time is closed at market. The log bears the intraday design out at position level: positions are measured in minutes rather than hours, and the longest hold in the whole log is under an hour.
Size, risk and compounding
Risk is a percentage of balance, not a fixed lot. The standard report starts at 5% with a 10% ceiling; the prop report at 1% with a 2% ceiling. Because the balance compounds across the test, with profit reinvested at the same percentage, the log's position sizes climb steadily and the dollars at risk per trade climb with them. Percentage sizing makes the later trades materially larger than the earlier ones, which is a different risk profile from a fixed-size test.
Recovery behaviour, stated plainly
The inputs carry Recovery_Factor and RecoveryFactor at 2.0 in both reports, besides Start_Risk and Max_Risk. A recovery multiplier escalates size after a loss up to the ceiling: in the standard set from 5% towards 10%, in the prop set from 1% towards 2%. The product page does not describe the mechanism, and the reports do not mark which trades were sized by it, so escalation and ordinary compounding cannot be separated in the published log. What the reports do establish is that DowX is not a flat-risk system.
News, and the sessions that produce nothing
The site says the system places no orders over news events. No news-related input appears in either report, so the promise rests on the two-minute window rather than on a filter a reader can inspect. The page also warns that many days bring no fill; the trade count in the report is far below one a day, consistent with a system that stands aside often, and a buyer should expect an equity curve that moves in short bursts rather than a steady line.
DowX's MetaTrader Parameters
No input reference is published for DowX, so the values below are transcribed from the Inputs block printed in both MT5 strategy-tester reports held in the archive on the product page, not from a documented default set. These are the values the vendor tested, and the page says settings can be adjusted per account. Parameter names keep their MT5 spelling.
| Input | Controls | Standard run | Prop run |
|---|---|---|---|
| NumberOfOrders | Order pairs submitted per session | 1 | 1 |
| OrderTime | Server time the stop orders are submitted | 16:30:02 | 16:30:02 |
| CancelAllTradesByTime | Server time unfilled orders are cancelled | 16:32 | 16:32 |
| CancelOpposite | Removes the untouched order once the other fills | true | true |
| CloseAllTradesByTime | Server time open positions are closed at market | 22:00 | 22:00 |
| Order1_SL | Stop distance from entry, in points | 9000 | 9000 |
| Order1_TP | Target distance from entry, in points | 9000 | 9000 |
| UseTrailingStop | Enables the trailing stop | true | true |
| TrailStart | Open profit, in points, at which trailing begins | 2500 | 2500 |
| TrailDist | Distance kept behind price, in points | 1000 | 1000 |
| TrailStep | Step size of the trailing stop, in points | 1000 | 1000 |
| BreakEven | Enables the move to break-even | false | false |
| BreakEvenAfterGain | Gain that would trigger the break-even move | 90.0 | 90.0 |
| BreakEvenLevel | Offset applied at break-even | 0.0 | 0.0 |
| Lot_Sizing | Selector between percentage-risk and fixed-lot sizing | 1 | 1 |
| Start_Risk | Risk per trade as a percentage of balance | 5 | 1 |
| Recovery_Factor | Multiplier applied to size after a losing trade | 2.0 | 2.0 |
| Max_Risk | Ceiling on risk per trade while recovery is active | 10 | 2 |
| StartLotSize | Lot size used when fixed-lot sizing is selected | 0.1 | 0.1 |
| MaxLotSize | Lot ceiling for the fixed-lot path | 0.4 | 0.4 |
| UpsideGap | Offset added by the block labelled PROP SCRAMBLE, upper order | 750 | 750 |
| DownsideGap | Offset added by the block labelled PROP SCRAMBLE, lower order | 750 | 750 |
On this symbol a point is 0.01 index points, so the 9,000-point stop and target are the 90.00 index points visible in the order log, and 2,500 points of trailing activation is 25.00. One discrepancy is worth flagging: MaxLotSize sits at 0.4 in both reports, yet the log carries positions many times that ceiling. The ceiling therefore appears to govern the fixed-lot path only, while percentage risk sizes without it — a reader who assumes MaxLotSize caps exposure would be wrong, and the point is worth confirming with the vendor.
DowX's Review Bottom Line
The evidence behind DowX is a vendor site, four externally hosted records the desk could not open, and two MT5 reports covering the same test window on one broker's feed. The reports are more than a teaser — two balances, two risk profiles, a full order log, a consistent trade sequence and a stated history quality — and none of it is verified live trading.
The system suits a trader already on MT5 who wants one index decision a day, keeps a US30 quote tight enough for a 90-point target to mean something, and is content to sit out the many sessions that produce no fill. It does not suit an MT4 user, a trader who wants diversification, or anyone who reads MaxLotSize as a cap on exposure: the log carries positions far above that ceiling.
Two facts belong in any decision: the equity drawdown on the standard settings is severe, and the deepest balance drawdown came from a single short burst of losses rather than from accumulated ones. Trading this or any Expert Advisor carries the risk of loss, and a backtest is a model rather than a promise. The decision stays with the reader — open the Myfxbook records, get the recovery and lot-cap behaviour confirmed in writing, and size the account so that a repeat of the tested drawdown is survivable.
Other Forex Robots from QuoTrader

MBT implements an automated breakout approach for XAUUSD that detects volatility windows and places directional trades with defined stop-loss and take-profit logic. It blends breakout detection with momentum filters and position sizing rules to capture trending moves while attempting to limit drawdowns.

The vendor's stated premise for ADR is that Gold's average daily range sets the frame for the next session: orders placed at the edges of that range should catch the day's expansion, and the stop and target should widen or contract with the same reading. The risk control is structural — one attempt a day, no re-entry, no averaging into a loser, no position carried into the next session.
The vendor's premise for DowX is that the Dow30's opening minutes produce enough displacement for a two-sided stop entry to catch a direction, and that a 90-point stop with a trailing exit takes most of the move before it fades. Nothing in the system forecasts direction; it is built to be present when the open resolves and to leave early when it does not.
Tags
Valery Trading
Tickmill
Algocrat AI
FXAutomater
WallStreet Forex Robot 3.0 Domination
Tick Data Suite
IC Markets
StrategyQuant X
Waka Waka
Perceptrader AI
Forex Diamond
Volatility Factor Pro
RoboForex
XM
HF Markets
InstaForex
Alpari
FX Scalper X
Forex Combo System
GPS Forex Robot
Golden Pickaxe
Forex Trend Detector
GrandCapital
Automated Forex Tools
Omega Trend
Broker Arbitrage
TradingFX VPS
AMarkets
Telegram Signal Copier
SMRT Algo
EasyAlgos AI
Quant Analyzer
AlgoCloud
Forex Trend Hunter
FXVM
Forex Gold Investor
Binance
Infinity Trader
Gold Miner
Sentinel AI
RayBOT
Gold Scalper PRO
LeapFX Trading Academy
ForexSignals.com
FxPro
ACY Securities
Zone Hunter Robot
Elirox
FX-Builder
Quant Data Manager
Commercial Network Services
FXCharger
News Scope EA PRO
Happy Forex
FXTM
BlackBull
Libertex
Smart Scalper PRO
Happy Bitcoin
Pump Trader Robot
WallStreet Recovery PRO
SlingShot
Dark Kronos
Vortex Trader PRO
Swing Trader PRO
Pepperstone
VPS Forex Trader
QHoster
FX Secret Club
Best Free Scalper Pro
Magnetic Exchange
Exness
StarTrader
Forex VPS
MTeletool
Trend Matrix EA
Trade Copier Station
Forex Robot Academy
Forex Robot Factory (Expert Advisor Generator)
ByBit
Database Mart
Gold Breaker
DARKEAS
Quant Tekel Funded
XAUBOT
ChartPrime
easyVPS
EGPForex
Risk
Forex trading can involve the risk of loss beyond your initial deposit. It is not suitable for all investors and you should make sure you understand the risks involved, seeking independent advice if necessary.
Forex accounts typically offer various degrees of leverage and their elevated profit potential is counterbalanced by an equally high level of risk. You should never risk more than you are prepared to lose and you should carefully take into consideration your trading experience.
Past performance and simulated results are not necessarily indicative of future performance. All the content on this site represents the sole opinion of the author and does not constitute an express recommendation to purchase any of the products described in its pages.
Sponsored By


Get Funded



Search Queries Cloud
BTC
in control
best free forex robot
أفضل إكسبرت
fx fx scalper
Fx scalper
waka waka
Fx stabilizer
原騰國際
UABTIC
fx scalper x
wallstreet forex
ProFX
forex diamond
waka
pfx scalper
Forex vps
switchback
algo pro
recovery
cross pro
discount
porsaj
waka waka news filter is disabled
futuretrading
Trailing stop
RENKO EA AUTO TRADER
trade copier
Copy trade
happy gold
future indikatoren
wall street
data
ARBITRAGE
Evening Scalper Pro
Forex inControl 3.0 Review
alpha striker
vision scalper
Me ta trader 5
Download Trailing Stop Forex Robot